VAT Registration in Montenegro
Here is a presentation of the VAT registration rules in Montenegro. Contact our lawyers in Montenegro if you want to start a business here.
VAT registration in Montenegro is mandatory for most economic operators. The procedure can be completed with the help of our local lawyers, especially if you are a foreign investor.
| Quick Facts | |
|---|---|
| VAT registration services available (YES/NO) | Yes |
Standard rate | 21% |
Lower rates | 15% (e.g. books, certain hospitality and accommodation services); 7% on basic food products, medicines, public transport; 0% available on exports, supply of gas for vessels on international transport |
| VAT registration requirements | 30,000 EUR turnover in the last 12 months |
| Registration time frame (approx.) | Approx. 2-4 weeks |
| VAT for real estate transactions | 21% rate for transfer of ownership for bulidings |
| Exemptions available (YES/NO) | Yes, financial services, healthcare services, education, radio broadcasting, religious services |
| Filing period | Monthly filings |
| VAT returns support (YES/NO) | Yes |
| VAT refund availability (YES/NO) | Yes, for non-residents purchasing goods from Montenegro |
| Local tax agent required (YES/NO) | Not mandatory, however, a local agent for foreign companies is required |
Who must register for VAT in Montenegro?
VAT registration requirements apply to both local and foreign economic operators (both companies and natural persons) that:
- undertake taxable activities on the Montenegrin territory;
- meet the registration threshold;
- engage in import/export activities and offer cross-border services.
NOTE: As of 1 April 2026, the sale of construction land with an issued building permit has become a VAT-taxable activity.
What are the requirements for foreign companies in terms of VAT in Montenegro?
Foreign companies must register for VAT in Montenegro as soon as they start operating through branches or subsidiaries. However, it is also possible to register for the tax as a foreign business without a permanent establishment.
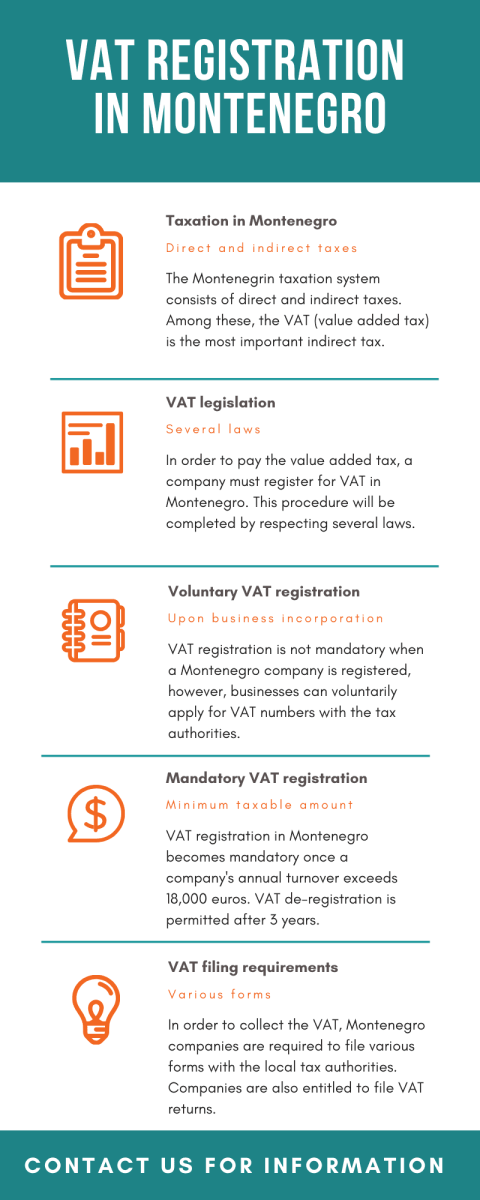
We also invite you to read about VAT registration in Montenegro in 2026 in the scheme below:
Is it necessary for foreign companies to appoint a fiscal representative in Montenegro?
Yes, foreign companies with no permanent establishment that supply services to non-taxable persons in Montenegro must appoint a VAT representative (rule clarified from 6 February 2026).
What are the VAT registration requirements for local companies in Montenegro?
Local businesses must register for VAT when reaching a minimum turnover of EUR 30,000 in a 12-month period.
Is voluntary VAT registration possible in Montenegro?
Yes, it is also possible to register for VAT voluntarily.
What is the VAT registration period for local and foreign companies?
Domestic businesses must register for VAT no later than 10 days from exceeding the minimum threshold. Foreign companies must register as soon as they start operating.
How long does it take to obtain a VAT code in Montenegro?
The Revenue and Customs Administration issues VAT numbers in 3 to 5 business days.
What is the format of a VAT code in Montenegro?
Country code ME + an 8-digit code, which is the tax registration code of a company.
What are the VAT rates in Montenegro?
At the level of 2026:
- 21% standard rate, applicable to most goods and services;
- 15% reduced rate, applicable to hotel accommodation, books, education, non-alcoholic beverages, catering services;
- 7% reduced rate, applicable to basic food, pharmaceuticals, water supplies, public transportation;
- 0% rate, applicable to exports and international transport.
You can also watch our video below:
What are the objectives of VAT taxation in Montenegro?
The following supplies of goods are levied with VAT in Montenegro:
- the supply of goods as a decision imposed by the authorities, including by the government;
- the supply of goods which are sold based on a contract which contains provisions on the payment of a commission;
- the supply of newly built constructions, as well as the transfer of ownership over immovable assets;
- the supply of natural resources to household and corporate consumers and which can include electricity, gas, air conditioning and energy for heating.
With respect to the supply of services, these can be considered liable for VAT if they are performed or contracted by another party. Among the services which are subject to the Montenegro VAT are the transfer of intellectual property rights, the supply of services based on a decision of the authorities and the supply of services by a taxpayer.
With respect to the import of goods, all products entering the country through the Montenegro Customs Authority will be subject to VAT.
Please contact our local lawyers, who will help you conform to the VAT rules of this country and will help you invest in Montenegro.
Vladimir Radonjic, Lawyer · 2 October 2026